November 7, 2026
MARKETS
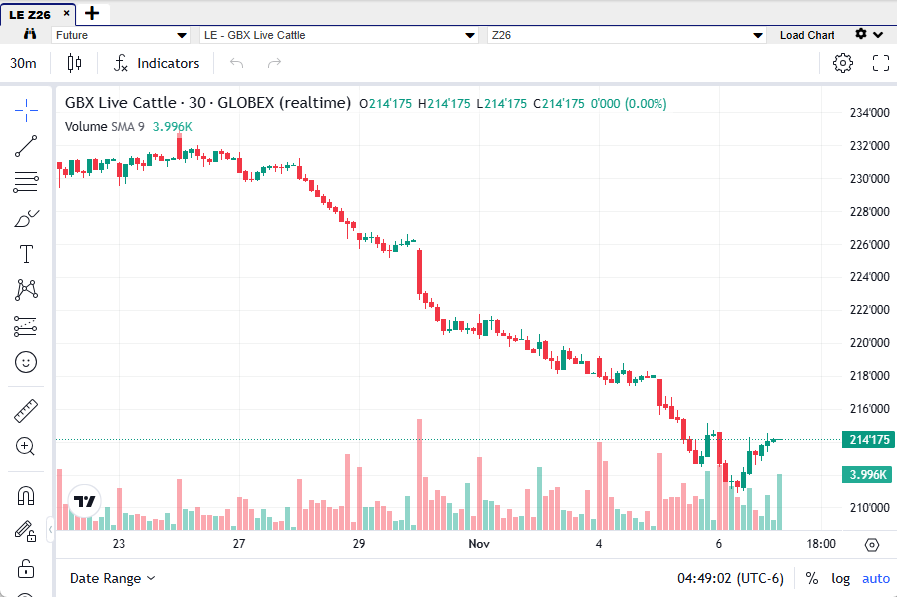
The week closed with a rout in cash and futures prices. Live sales in the north ranged from $208-$218 with weight as the major determinant of price. Dressed prices ranged from $330-$340. Trade developed in Kansas and Texas at $218 with the four state mandatory report confirming these numbers in a broader distribution. Northern prices continue to lag the south where ownership is generally in stronger bargaining hands and weights more appropriately conform to buyers interest. No one ever doubted the packer’s ability to trade off of any flaw in a group of cattle no matter how material.
Lenders rolled out the latest AI mark to market model and will be calling cattle owners next week for additional margins. The wildcard no one can answer is whether the excess numbers and weights of cattle in the north are cleaned up. Sellers, reading media stories of El Nino winters, were determined to lighten their feedlots of heavy cattle even with some covered with mud.
This week’s comprehensive fed cattle report showed a decline in carcass weights and quality grading — some indication of getting a handle on heavy cattle in the north. Generous packer margins and improved efficiency in plant utilization rates also will help clean up overweight cattle.
This week slaughter volumes was 534,000 head — 9,000 under the previous week and 35,000 under last year. The processors are turning the management of the weekly slaughter number into a professionally orchatrated work of art — holding beef prices in check while breaking the cash markets leading to some of the best margins this year. The weekly slaughter continues to reflect efficient plant utilitization. Box prices seem to have found a trading level balanced with a weekly slaughter volume of 530,000 to 540,000 head. Cow slaughter continues to increase weekly but remains under prior year. Processors have maintained profitability since July — the longest period during the past few years.
Benchmarking. On Tuesday of each week, USDA releases a weighted average price report for all cattle sold the previous week. The report summarizes the distributed price levels for each category of sale such as Negotiated/Formula/Forward Contracts. Beef producers are able to measure the marketing price for their cattle compared to the national averages.
The Comprehensive Fed Cattle Weekly Report offers the most current information on the current status of fed cattle being harvested. The report is published each Tuesday and includes the previous week’s change in carcass weights and quality grading. The latest report shows carcass weights at 962#, down 3# from the prior week, and 12# heavier than last year. The combined steer and heifer weights can easily be influenced when the proportion of steers to heifers in the weekly slaughter changes. Quality grade was down .4% from the previous week at 87.5. The quality grade remains near historic highs as cattle are fed to heavier weights.
The Weekly Steer and Heifer Grading Report reflects regional supplies of choice and prime cattle and often is determinative of regional differences in live prices. The report also indicates the current status of fed cattle offerings in each area.
Forward Cattle Contracts: Forward contracts are always a portion of the inventories the processors maintain for slaughter. Offered basis levels will move up and down as processors want to add to forward contracts or not. The driver in forward purchases of cattle will always be forward sales of beef. Packers will always be willing to take a price risk off the producer’s plate in return for an extra margin. The movement of futures prices, either up or down, will relate to the number of forward contracts.
Formula and Negotiated Grids. The Price and Distribution Report delineates the various selling methods and net results.
The Cattle Contracts Report details the percent of contracts by volume of cattle and by number of contracts for selling cattle. Formula selling that was once the largest marketing method and still is, but is losing ground to negotiated grids where the premiums and discounts are set but the base price is negotiated.
Fluctuating commodity prices have always presented a problem for restauranteurs. No restaurant wants to continually re-price items on the menu. Consumers are attentive to price increases and quickly notice upward pricing. Welcome to the world of a workaround. Some restaurants have opted to post a notice in small print at the bottom of a menu informing diners of a special surcharge of xx% added to the bill because of high fuel and labor costs.
The Cutout. The lean beef prices have struggled to hold ground under pressure from the imported beef. Cow slaughter is increasing seasonally. This past week’s slaughter volume helped improve plant untilization and efficiency. Slaughter volumes will continue to be dictated by processing margins and government intervention.
It is important to remember that spot box prices are much like spot cash prices for live cattle. Most boxes are sold under formulas and do not always have the same fluctuations as the spot market.
Replacement markets
Video and live auctions set the tone this week with sharply lower replacement prices. Many groups of cattle were POed and will reappear on future sales. Buyers never see the declines as sufficient. Margins remain near impossible for future promises of profit. Wheat fields across the southern plains are ready to receive cattle and it is apparent than many of those grazing opportunities will be left empty.
Land owners and operators across the southwest asking cattle operators for cattle are finding little interest. The price of the gain for cattle placed on pasture has drifted lower. Past pasture rates have reached $1/pound for the gain including care but this year some offers are half that number. The grazers closely examining the future outcome of today’s purchases, based on deferred cattle futures, are not finding a financial rewards at the end of the line. Much of the nation’s farm tracts will be left empty of cattle reserving the crop to be harvested for grain.
Short supplies of replacement cattle is also moving the needle on marketing strategies. Many stocker operators are transitioning into larger weights on pasture. This has triggered sharp increases the purchase of cattle weighing between 550-650# for outside grazing. The purchase of small volumes of 400# cattle is difficult and costly and sometimes risky from a health standpoint.
Feedlots are in the early stages or rightsizing occupancy levels. Most feedlots have been operating at reduced capacity and many smaller feedyards are empty but right sizing will require closing some facilities. The process has started and will continue through next year. The nation’s largest feedyards are dominated by operating entities owned by Wall Street investment firms and those firms aren’t friendly to capital infusions or negative returns.
Seasonally health problems can occur anytime with the stress of weaning. The fall is the most stressful season for unweaned calves and many operators cringe when healthy calves on arrival turn sick. The penalty suffered on freshly weaned calves is often an usually large death loss. Not only can death loss percentages jump, but also sick calves present a constant labor requirement and long term performance impairment. A $50 cwt. spread between weaned and unweaned calves is large, but sometimes justified. The spreads between weaned and unweaned calves is widening. Knowing more about the background of new purchases can be helpful including full health records.
The Drought Monitor is a map showing regions of the country under stress for lack of normal rainfall. The map is compiled over a week and updated every Thursday with data collected through Tuesday of that week.
Compared to last week: True yearling type feeder steers and heifers lightly tested and 4.00-12.00 lower. Sixty day weaned feeder type cattle selling sharply lower. Demand is moderate at best. Cattle futures turned negative midweek last week and fell out of bed on Friday. The Live cattle futures trading just lower while feeder futures trading some higher. Steer and heifer calves 10.00-20.00 lower on lesser quality, some to 30.00 lower. Demand for calves is further limited as a cold front is moving thru later this evening bringing storms, cooler temps and strong
north winds. Quality mostly average. Some cattle beginning to fill up ahead of the storms. Supply included: 100% Feeder Cattle (49% Steers, 44% Heifers, 7% Bulls, 0% Beef/Dairy Heifers). Feeder cattle supply over 600 lbs was 43%
Compared to last week: Feeder steers 10.00-20.00 lower. Instances to 30.00 lower but quality and days weaned a factor. Feeder heifers not well tested but a lower undertone noted. Demand moderate. Steer and heifer calves 5.00-15.00 lower. Steers weighing 450-550lbs were 20.00 higher. Quality mostly plain to average with best demand for the few better quality calves. CME futures are lower again. Wet and cooler conditions had buyers cautious on Tuesday. Supply included: 100% Feeder Cattle (49% Steers, 41% Heifers, 10% Bulls). Feeder cattle supply over 600 lbs was 51%.
Feeder Cattle Cash Index. The index is tracking the moves in cash prices. The Cattle Report has updated index reporting to provide a daily graph showing changes in price of the index.
Video and Internet Replacement Cattle Auctions. The movement from traditional private treaty sales to Internet auctions has been slow but steady. Producers have chosen this option as the primary marketing tool for most of the cattle offered in the replacement markets. The market that was once dominated by one firm has seen new competition from multiple trade platforms.
National Weekly Feeder Summary released on Friday of each week tracks the national prices by region for last week.
Grain Futures. Corn prices drifted lower, but basis levels have increased. The current basis level is near +$1.10 in Guymon, Oklahoma — basis the December contract.
THE ELECTION
Politics has built a party history featuring Republicans as more business friendly than Democrats. The change of control in Congress went further than the legislative branch and changed many red state government leaders. The economy and war were on the minds of voters, but close behind was voter reaction to corruption.
America has built world leadership from innovation championed by competition in a capitalist society. Trump has distorted the system making many believe his style of self-dealing and insider advantage is representative of capitalism. This has created the new branch of the Democratic party – the Democrat Socialists.
The beef industry is built on capitalism and free markets. It thrives because individuals can own property and manage it to best advantage. It suffers at the hands of governmental interference. Rarely does the government know best and frequently government interference results in unintended consequences.
It is too early to determine what the impact of change of control in the government will mean to the beef industry. Our system of governing is designed for checks and balances between the three branches of government, and the election will restore balance. The most favorable outcome would be a return to free markets and dependence on price signals to drive supply.
CARDINAL RULE FOR COMMODITY TRADING
“IF IT IS OBVIOUS, IT HAS GOT TO BE WRONG!”
CATTLE REPORT LIBRARY
Change is a necessity for any sustainable industry and sometimes necessary changes encounter obstacles in the form of stalwarts who refuse change. The Cattle Report has created a library page of opinions pieces published on these pages advocating fundamental and structure changes for the industry.
NOTE TO READERS
Sections of the newsletter are designed with hyperlinks to the appropriate source pages. The hyperlinks are in light blue within the report.
EXPLANATIONS OF BREAKEVEN/CLOSE OUT TABLES
Regional differences in grain and cattle basises create a difficulty in modeling a national composite for current close outs or a proforma forward look at a breakeven. Readers should consider your own area for adjustments to these models. Most calculations are basis relevant prices in Guymon, Oklahoma.
CURRENT BREAKEVEN PROJECTION
The Cattle Report introduces the FEEDER METER. The report estimates profit or loss for currently purchased feeder steers and projects a result 180 days out. The chart is interactive and updated every 15 minutes in real time based on changes in futures markets in grain and cattle. Corn basis information is based on current trade prices adjusted every two weeks. Feeder prices are based on the USDA index price for 800# steers and fed cattle sales are $2 cwt. premium the appropriate futures contract.
CURRENT CLOSE OUT
The Cattle Report estimates current profit or loss on cattle placed on feed 180 days ago. This report generated from industry averages attempts to simulate a typical close out based on the feeder index for 800# steers 180 days ago. The close out assumes grain was purchased at market each month. Selling prices and interest rates are based on prevailing benchmark quoted prices. This chart will change weekly.
Contact Us
The CATTLE REPORT will strive to answer all emails. Our editorial views are not always popular and sometime create controversy and are sometimes flat out wrong.